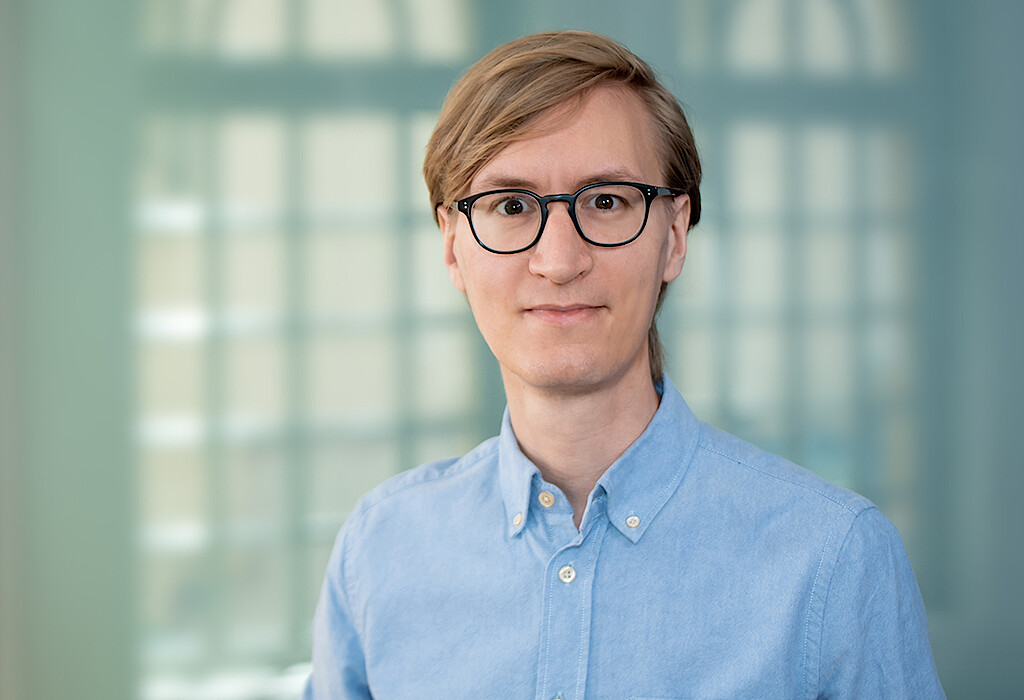
Professor Dr. Daniel Streitz

Professor Dr. Daniel Streitz
Aktuelle Position

seit 1/23

Leiter der Forschungsgruppe Finanzintermediäre und die Realwirtschaft

Leibniz-Institut für Wirtschaftsforschung Halle (IWH)

seit 4/21

Senior Research Advisor der Abteilung Finanzmärkte

Leibniz-Institut für Wirtschaftsforschung Halle (IWH)

seit 4/21

Professor für Volkswirtschaftslehre

Friedrich-Schiller-Universität Jena

Forschungsschwerpunkte

  • Finanzintermediation
  • Unternehmensfinanzierung
  • Geldpolitik

Daniel Streitz ist seit April 2021 Senior Research Advisor am IWH und Professor an der Friedrich-Schiller-Universität Jena. Zu den Schwerpunkten seiner Forschung gehören die Finanzintermediation und die Unternehmensfinanzierung.

Daniel Streitz studierte an der Westfälischen Wilhelms-Universität Münster und promovierte an der Humboldt-Universität zu Berlin. Bevor er zum IWH kam, war er Assistenzprofessor an der Copenhagen Business School.
Ihr Kontakt

Professor Dr. Daniel Streitz
- Abteilung Finanzmärkte
Nachricht senden +49 345 7753-735 Persönliche Seite

Publikationen

Zitationen
1176

cover_journal-of-financial-economics.png

Out of Sight, out of Mind: Divestments and the Global Reallocation of Pollutive Assets

Tobias Berg Lin Ma Daniel Streitz

in: Journal of Financial Economics, Vol. 182 (August), 2026

Abstract

We document a global reallocation of pollutive assets as a response to investor pressure: large firms facing increased investor pressure divest foreign-located pollutive assets to firms that are less in the limelight. There is no evidence of increased engagement in any other emission reduction activities. We estimate that 369 million metric tons (mt) of CO2e are reallocated via divestments in the post-Paris Agreement period. Our results indicate that investor pressure to decarbonize reshapes the global conglomerate structure of large firms.

Publikation lesen

cover_review-of-financial-studies.png

Corporate Loan Spreads and Economic Activity

Anthony Saunders Alessandro Spina Sascha Steffen Daniel Streitz

in: Review of Financial Studies, Vol. 38 (2), 2025

Abstract

We investigate the predictive power of loan spreads for forecasting business cycles, specifically focusing on more constrained, intermediary-reliant firms. We introduce a novel loan-market-based credit spread constructed using secondary corporate loan-market prices over the 1999 to 2023 period. Loan spreads significantly enhance the prediction of macroeconomic outcomes, outperforming other credit-spread indicators. We also explore the underlying mechanisms and differentiate between borrower fundamentals and financial frictions. Evidence suggests that supply-side frictions are a decisive factor in the forecasting ability of loan spreads.

Publikation lesen

cover_the-review-of-corporate-finance-studies.png

Credit Supply Shocks: Financing Real Growth or Takeovers?

Tobias Berg Daniel Streitz Michael Wedow

in: Review of Corporate Finance Studies, Vol. 13 (2), 2024

Abstract

How do firms invest when financial constraints are relaxed? We document that firms affected by a large positive credit supply shock predominantly increase borrowing for transaction-based purposes. These treated firms have larger asset and employment growth rates; however, growth entirely stems from the increased takeover activity. Announcement returns indicate a low quality of the credit-supply-induced takeover activity. These results offer the possibility that credit-driven growth can simply reflect redistribution, rather than net gains in assets or employment.

Publikation lesen

Arbeitspapiere

cover_CEPR-discussion-papers_20499.png

The Exchange Rate Between Monetary and Fiscal Policy: What Is an Interest Rate Cut Worth?

Ulf Nielsson Jesper Rangvid Farzad Saidi Fabian Seyrich Daniel Streitz

in: CEPR Discussion Papers, im Erscheinen

Abstract

When monetary policy is constrained, how large a scal transfer substitutes for a given interest rate cut? Using full-population Danish administrative data, we estimate household consumption responses to adjustable-rate mortgage resets and to unanticipated cash inheritances. A 1 percentage point rate cut maps to uniform transfers of approximately $1,000 per person over 5 years, totaling 1.3% of GDP. These macro-equivalent policies operate through distinct balance-sheet channels with dierent distributional incidence: rate cuts disproportionately stimulate high-income mortgage holders, while transfers are progressive. Marginal propensities to consume vary only modestly across income and liquid-wealth distributions, limiting eciency gains from targeting.

Publikation lesen

cover_SSRN.png

Too Poor to Be Green? The Effects of Wealth on the Residential Heating Transformation

Tobias Berg Ulf Nielsson Daniel Streitz

in: SSRN Working Paper, 2024

Abstract

Using the near-universe of Danish owner-occupied residential houses, we show that an exogenous increase in wealth significantly increases the likelihood to switch to green heating. We estimate an elasticity of one at the median of the wealth distribution, i.e., a 10% increase in wealth increase raises green heating adoption by 10%. Effects are heterogeneous along the wealth distribution: all else equal, a redistribution of wealth from rich households to poor households can significantly increase green heating adoption. We further explore potential channels of our findings (pro-social preferences, financial constraints, and luxury goods interpretation). Our results emphasize the role of economic growth for the green transition.

Publikation lesen

cover_ssrn_4602788.png

The Art of Timing: Managing Sudden Stop Risk in Corporate Credit Markets

Lin Ma Daniel Streitz Fabrice Tourre

in: SSRN, im Erscheinen

Abstract

High yield firms aggressively exercise the call option embedded in their bonds. We construct a new measure of option moneyness and show that firms efficiently exercise the interest rate and spread option implicit in these contracts. Controlling for moneyness, firms frequently prepay bonds and issue new debt if rollover risk is high. We develop and estimate a structural model to quantify the costs and benefits of dynamically managing this risk. The ability to use callable debt almost entirely dissipates dead-weight losses from rollover risk. Creditor-shareholder conflicts re- duce the effectiveness of this dynamic hedging strategy for highly levered firms.

Publikation lesen
Mitglied der Leibniz-Gemeinschaft LogoTotal-Equality-LogoGefördert durch das BMWK